

Fairy tales are full of princes and princesses being transformed into animals by wicked witches. A handsome prince becomes a beast. A royal heir is reduced to an ordinary frog. The spell is eventually broken, and they reclaim their rightful place.
But financial markets, however, rarely follow fairy-tale endings and the rise of AI may be casting a very different spell.
Some of the technology companies, long regarded as the handsome princes of the digital age, are finding that the AI magic could be turning them into frogs.
The Tech Princes
When we think of technology companies, our minds often jump to Silicon Valley start-ups - small teams of coders building the next disruptive app from a garage.
Investors see something rather different. Today’s technology sector is dominated by royalty: companies like Google, Apple, Amazon and Meta. These are firms with fortress-like market positions, extraordinarily high profit margins and balance sheets overflowing with cash.
Their kingdoms are built on intangible assets rather than physical ones. Intellectual property, software, algorithms, customer relationships and vast datasets have become far more valuable than factories, warehouses or aircraft. Aside from their growing cash mountains, many of these businesses have historically owned surprisingly few tangible assets.
This asset-light, cash-generative model became the defining characteristic of the Magnificent Seven. They were the undisputed princes of the digital economy - commanding their industries, dominating investor portfolios and appearing almost impossible to dethrone.
The AI Curse?
The issue is that the rise of AI is quickly changing the nature of modern technology firms. The huge AI infrastructure buildout is fundamentally shifting the business model from an asset-light structure to one characterised by physical assets: data centres, cooling systems, networking equipment and power infrastructure.
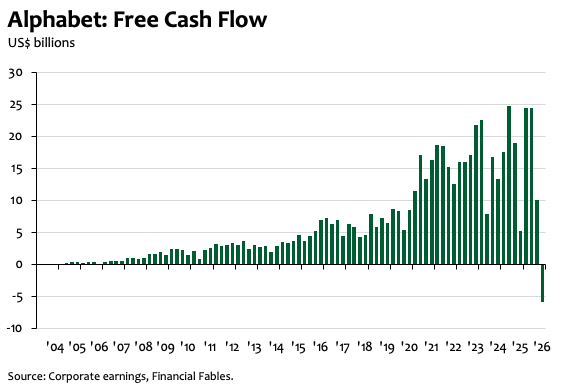
And this buildout of hard assets is expensive. Take Alphabet, Google’s parent company, which released its second-quarter earnings this week. We can already see a marked deterioration in its free cash flow - the cash left over after funding both day-to-day operations and capital investment. As shown in the chart below, free cash flow has turned negative for the first time on record and it is expected to stay there as the firm continue to spend billions in the AI race.
Now, this shift is not in itself a problem. Investments made today that generate financial returns tomorrow are often exactly what shareholders should want to see. But it does start to put a few warts on the faces of these once-handsome tech princes.
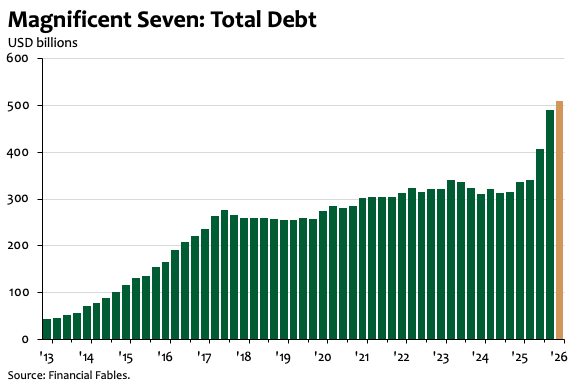
As the chart below shows, the debt piles of these once-Magnificent Seven have begun to surge in order to fuel expensive AI buildouts. Furthermore, firms such as Meta and Google are actively contemplating equity raises - something that would have been almost unthinkable just a few years ago - in order to keep AI investment flowing.
Whether this AI spending ultimately pays off remains to be seen. But it does raise a more fundamental question for investors. If technology companies are becoming more capital-intensive, should we continue to value them as the asset-light businesses they once were?
How to Value Frogs
If asset-light princes are being turned into infrastructure-heavy frogs, then investors may need to think more carefully about how these companies should be valued, particularly firms such as Alphabet, Amazon and Microsoft, which are investing heavily in the physical infrastructure behind AI.
For years, these companies were rewarded with premium valuations because they combined rapid growth with remarkably asset-light business models. Once the software was built, it could be sold to millions of customers at relatively little additional cost, allowing profits and cash to compound with limited ongoing investment.
But data centres are not one-off investments. They require constant maintenance, consume vast amounts of power and, perhaps most importantly, have a finite economic life. Servers, networking equipment and AI chips must all be replaced as technology advances. In other words, today's capital expenditure risks becoming tomorrow's maintenance expenditure.
That doesn't immediately make these tech companies bad businesses but it does mean they start to share some of the characteristics of infrastructure providers and utilities - businesses that require continual capital investment simply to maintain their competitive position.
And that matters because investors have historically valued those businesses differently. Asset-light technology firms have commanded premium valuation multiples because they can grow with relatively little additional capital. Infrastructure-heavy businesses, by contrast, have typically traded on lower multiples because a larger share of their cash flows must be reinvested just to keep the engine running.
So it seems the real curse of AI is that it slowly turns them into infrastructure-heavy frogs - meaning investors may no longer value them like royalty.
Gone Fishing
As long-term subscribers will know, I usually take August off from writing to recharge and focus on a few other projects.
I’ll be back in September with more Financial Fables, market insights and updates. Until then, thank you for reading, and I hope you have a fantastic summer.
See you in September!
Disclaimer: The information provided in this blog post is for general informational purposes only and should not be construed as financial, investment, or professional advice. The content is not intended as a solicitation, recommendation, endorsement, or offer to buy or sell any securities or financial instruments. Any reliance you place on such information is strictly at your own risk. Always consult with a qualified financial advisor or professional before making any investment decisions. The author and the website assume no responsibility for any losses or damages that may result from the use of or reliance upon the information provided in this blog post.
Subscribed. We're Sukrat and Gaurav, and we built Bufflo because we were tired of rebuilding the same screener filters every morning across four tabs.
Now we write about trading workflows and what we're building on our Substack. Subscribe to Bufflo if that sounds useful.
You asked the right question, "Do we need to re-think how we value Amazon, Microsoft and Google?"
They are NOT all the same. Amazon was never valued as an "asset-light" company. Only Microsoft and Google, to some extent, were.
People focus on growth and earnings, and forget the shape of balance sheet. Earnings are a mechanism for the voting machine, the balance sheet is the weighing machine.